Industry Report Q2 2025



Executive Summary
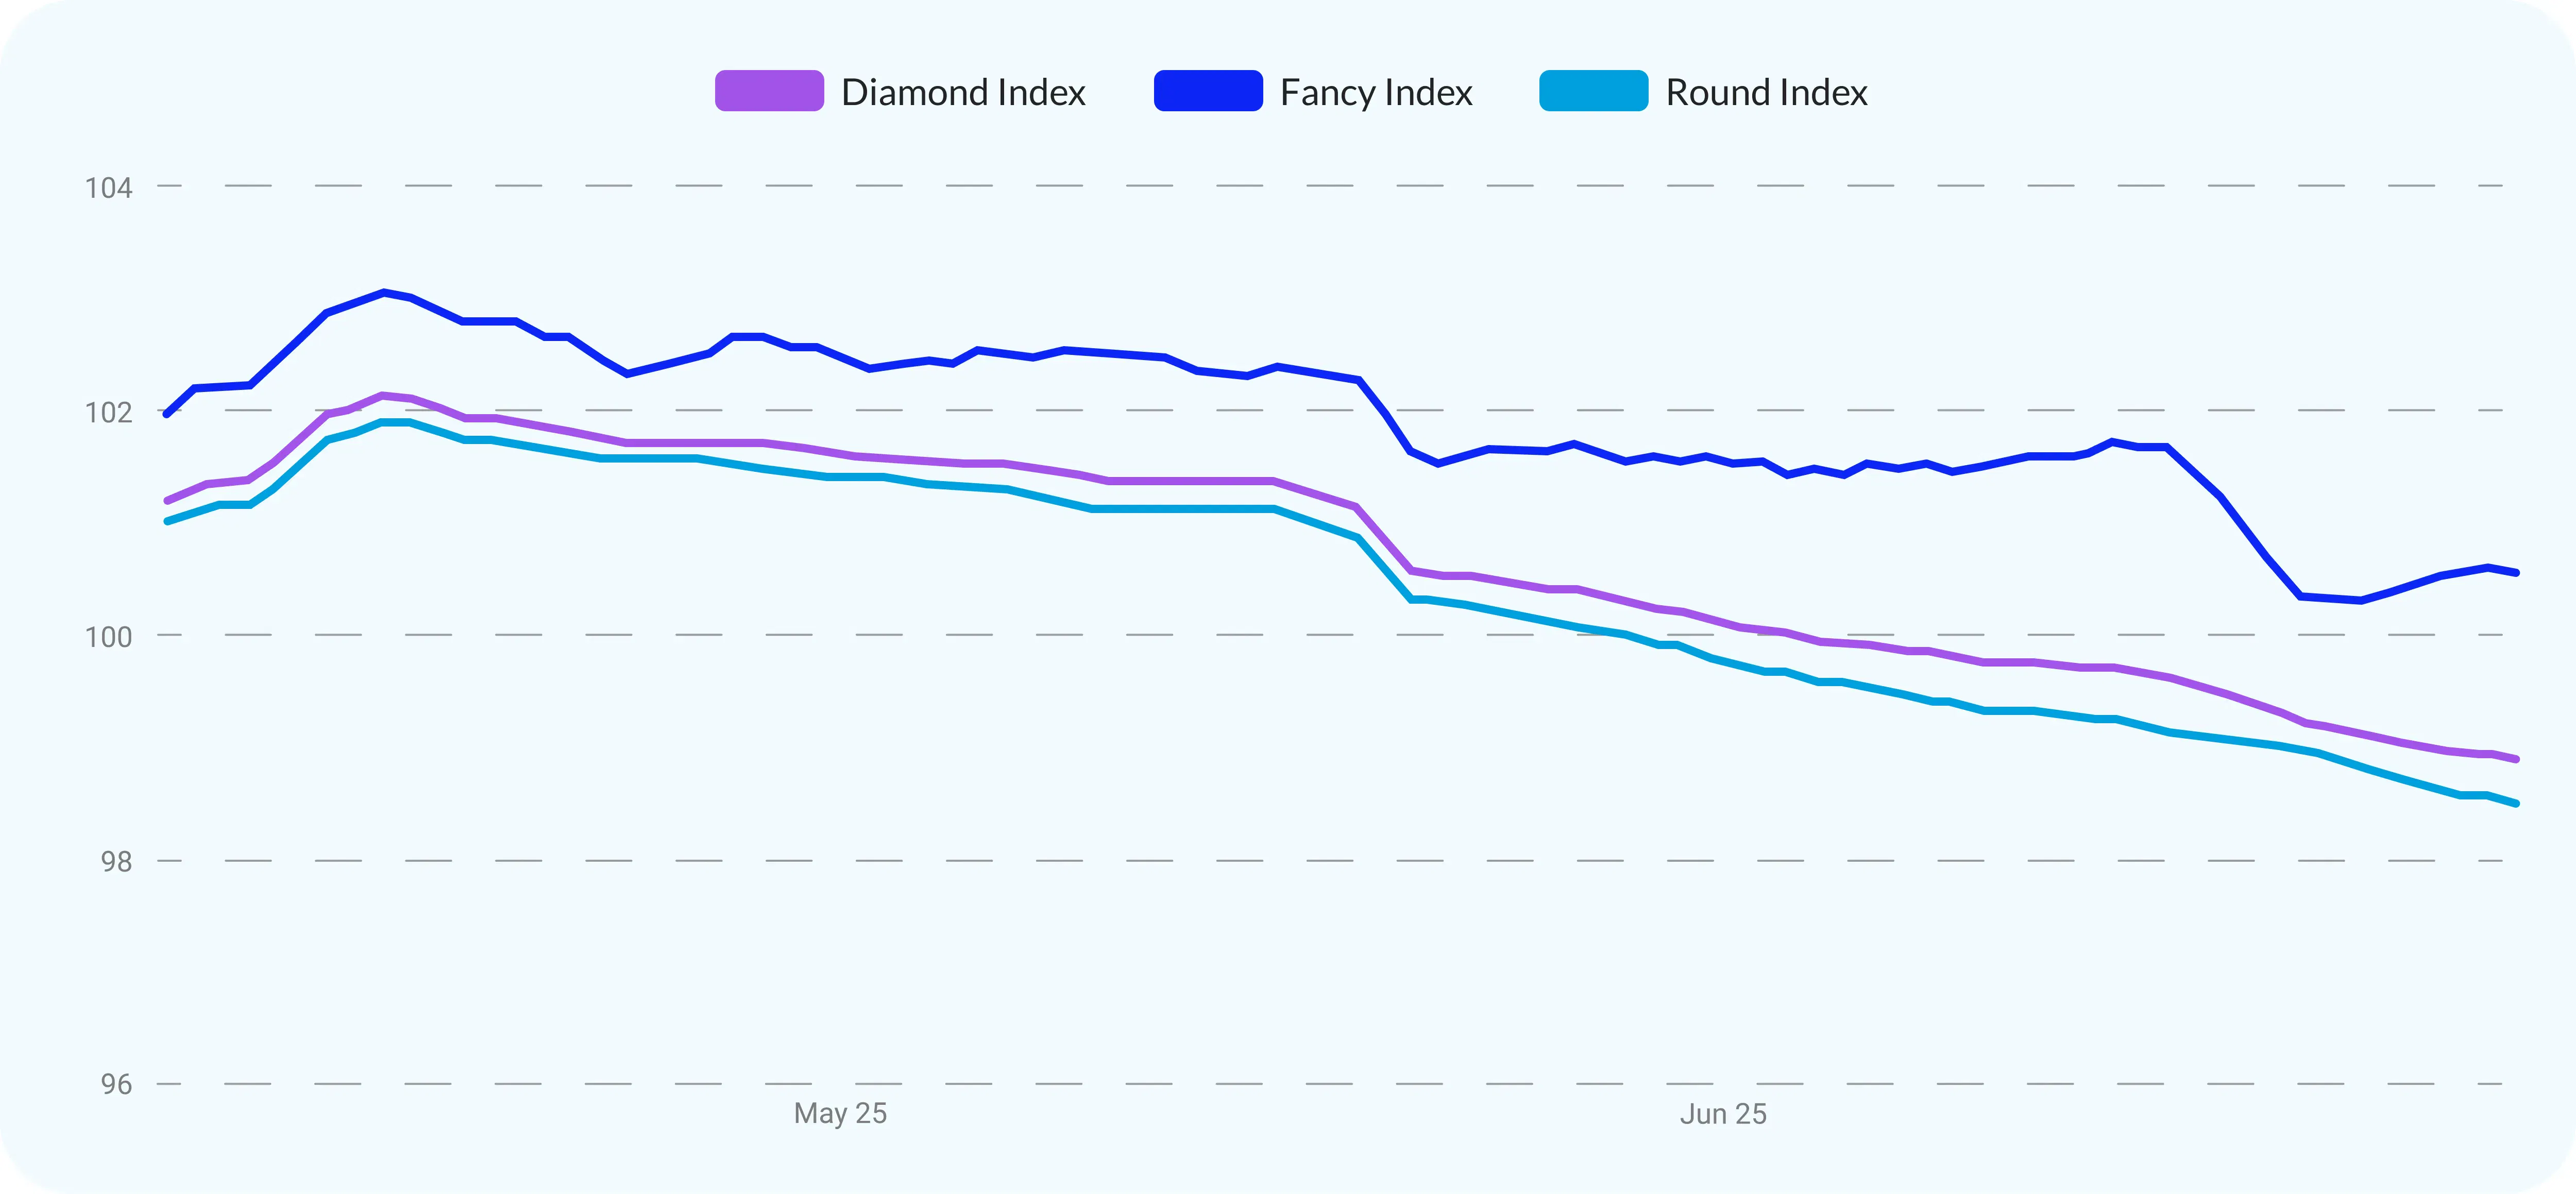
Q2 2025 continued the market’s trend toward stabilization. Across the board, prices remained steady, with the Diamond Index dipping by just 1.11%, a modest shift that reflects a maturing market, where both buyers and sellers are adjusting to new norms rather than reacting to volatility.
Round goods, particularly in the 1ct to 3ct range, showed solid resilience, even as inventory levels rose significantly in several categories. Notably, 2ct and 3ct stones saw large supply increases without triggering major price decreases, indicating that demand for these goods is beginning to strengthen and pricing is starting to firm. However, if supply continues to rise without a corresponding lift in demand, downward pressure on prices may follow.
While there was widespread concern that Q2 could bring sharp declines due to the uncertainty surrounding US tariffs, the market held up stronger than expected. This resilience under pressure is a positive signal, and should tariffs be lifted, the market appears well-positioned for a potential recovery, even setting the stage for price increases in the months ahead.
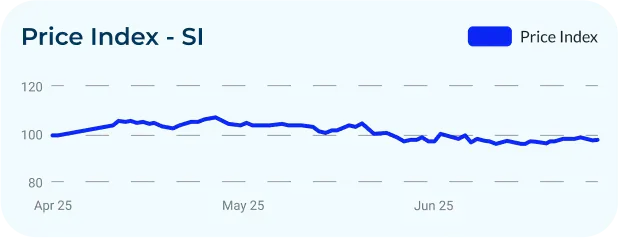
SI clarity stones, which came under pressure in Q1, also showed signs of rebalancing. While price declines continued in some categories, they were more moderate and more controlled than in the previous quarter.
As the trade watches tariff developments closely, UNI Diamonds’ market insights remain critical for navigating uncertainty, identifying opportunity, and trading with confidence.
Overview of the Industry
Diamond Index
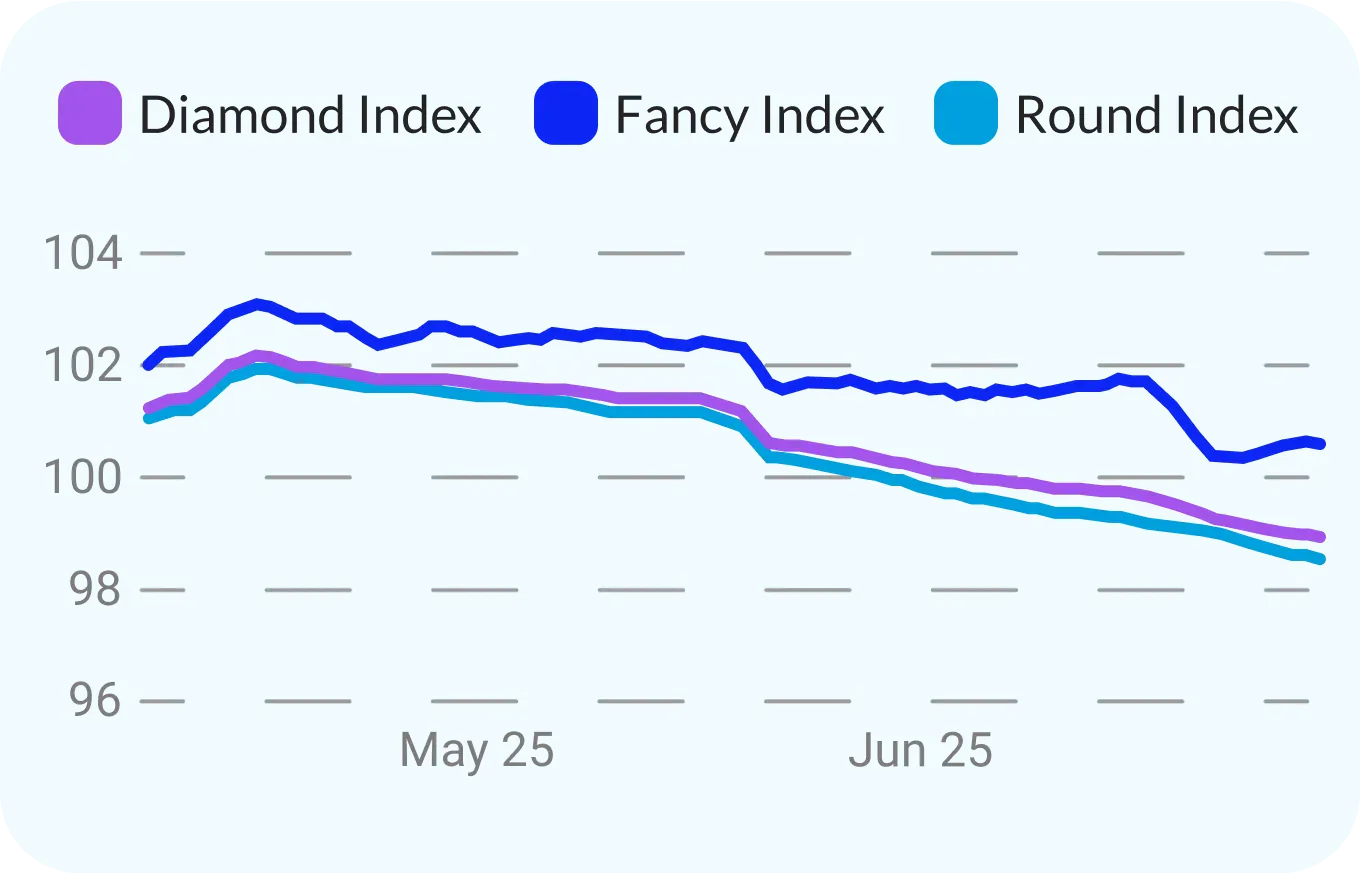
The diamond market remained stable throughout Q2 2025, with the Diamond Index decreasing by just 1.11%. This brings the year-to-date decline to 3.4%, reflecting a market that continues to adjust gradually rather than react with volatility. The overall pace has remained balanced, with no sharp swings in pricing, suggesting that supply and demand are moving in sync. That said, smaller stones experienced more notable price declines, particularly in SI categories, which weighed on the overall index.
Round Index
The Round Index fell by 1.5% over the quarter, continuing the slow and steady movement seen in Q1. Pricing across this segment remained relatively even, with no major disruptions or spikes. This consistency reflects a cautious but composed trading environment, even as global conditions evolve. Year-to-date, the Round Index is down 4.5%, showing the cumulative impact of sustained price pressure over the first half of the year.
Fancy Index
The Fancy Index rose by 0.5% during Q2, continuing the upward trend seen in recent months. Although slightly more movement was recorded in Fancy shapes compared to Rounds, the changes were still moderate and part of a broader pattern of market stability. Year-to-date, the Fancy Index is up 1.6%, highlighting continued interest and relative strength in this segment.
Round 0.30ct Stones
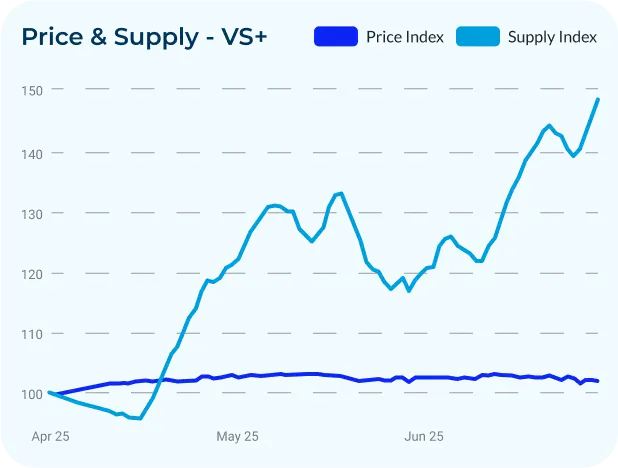
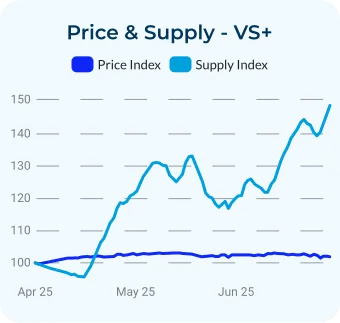
In Q2 2025, the 0.30ct segment reflected overall market stability, with moderate shifts in both price and supply across clarity categories.
VS+ stones showed consistent performance throughout the quarter. Prices remained stable, ending with a small but steady increase of 1.85%. Almost all segments within this category saw price increases, with the exception of VVS+ D-E-F stones, which recorded a 6% decline. Supply rose notably over the quarter, ending Q2 up by 48%. While prices held firm despite the increase, the sustained rise in availability may start to put downward pressure on pricing if demand doesn’t accelerate in the coming months.
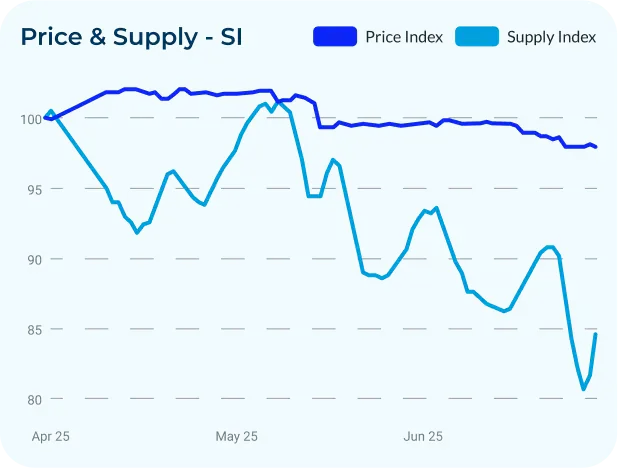
SI stones also reflected market steadiness. Prices ended the quarter with a modest overall decrease of 2%, while supply declined by 15.4%. These controlled shifts in both price and inventory suggest that the SI category, while still sensitive to demand, is showing signs of stabilization.
Round 0.50ct Stones
The 0.50ct segment continued to show signs of stabilization in Q2 2025, with modest price changes across clarity categories and clear shifts in supply levels.
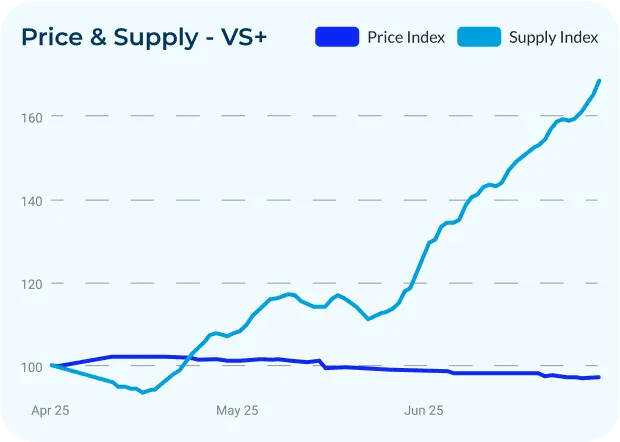
VS+ stones remained largely stable through the quarter. Overall, prices recorded a slight decrease of 3%, with only minimal fluctuations across the three months. Supply rose steadily throughout Q2, ending the quarter up 68%. While prices stayed relatively firm, the consistent growth in inventory could begin to pressure this balance if demand does not pick up.
SI stones continued to face pricing pressure in Q2, ending the quarter down 5.9%. Supply increased by 28% over the same period, raising the risk of oversupply if demand doesn’t strengthen in the months ahead.
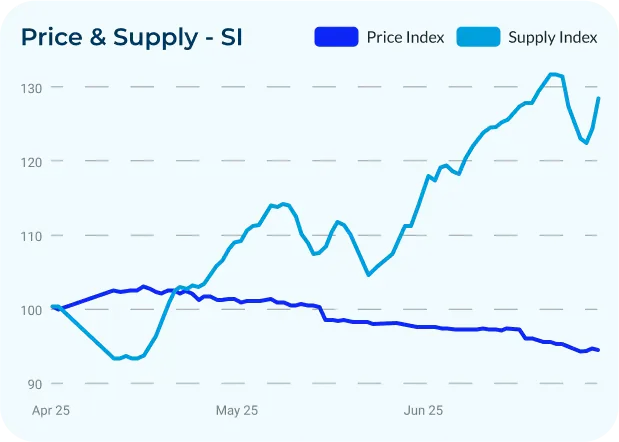
Round 1ct Stones
The 1ct category continued its path toward stabilization in Q2 2025, following a quarter of mixed trends in Q1. While Q1 saw a 4.5% decline in VS+ prices and a 5.5% decrease for SI stones, Q2 brought significantly milder movement, signaling a more balanced market.
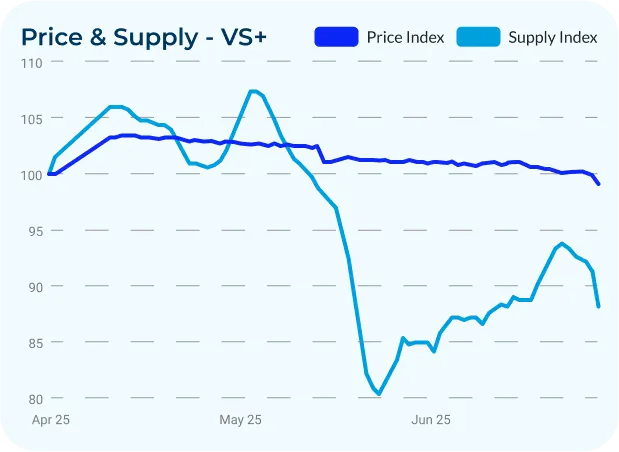
VS+ stones showed strong signs of stability in Q2. Prices ended the quarter down just 1%, a major improvement from the 4.5% decrease seen in Q1. Supply fell by 11.8%, compared to a 32% drop in Q1. The smaller price movement and reduced volatility suggest this segment is beginning to stabilize and maintain buyer confidence.
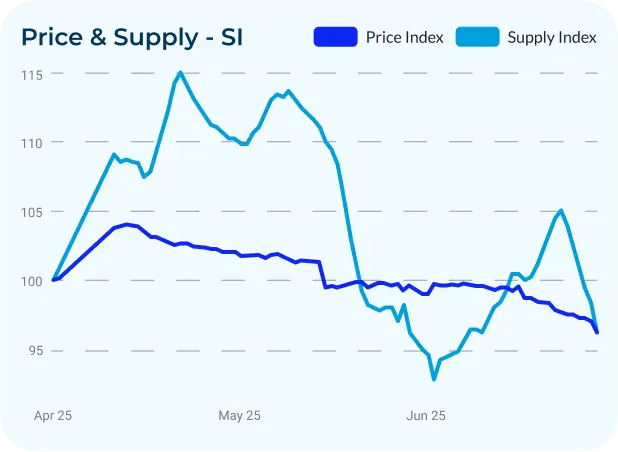
SI stones also showed more moderate movement in Q2. Prices declined by 3.9%, compared to a 5.5% drop in Q1. Supply decreased by 3.8%, versus a 21.6% reduction in the previous quarter. The easing pace of both price and supply adjustments suggests this category may be entering a turning point, and is one to watch closely in the months ahead.
Round 2ct Stones
The 2ct category remained one of the most stable segments in Q2 2025, continuing the positive momentum seen in Q1 and throughout 2024.
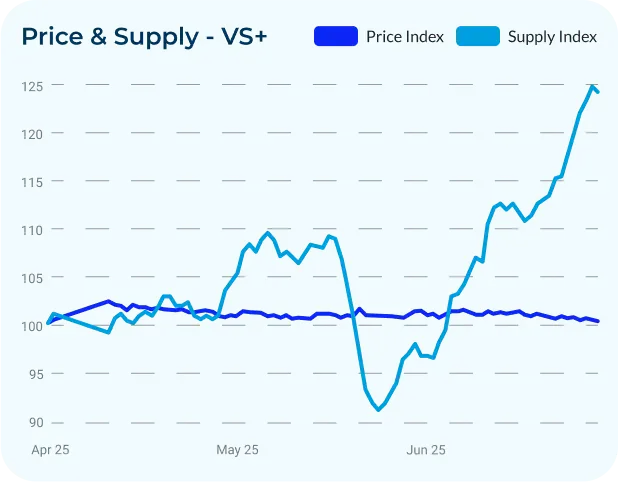
VS+ stones showed minimal price movement across the quarter. After small fluctuations, prices ended Q2 with a slight overall increase of 0.13%, reinforcing the segment’s position as one of the most stable in the market. This follows a similarly stable Q1, where VS+ prices declined by only 0.3%. Supply rose by 24% over the course of the quarter, compared to a 29.6% decrease in Q1. The fact that pricing held steady despite a notable supply increase suggests strong underlying demand and a well-balanced market for higher-clarity 2ct stones.
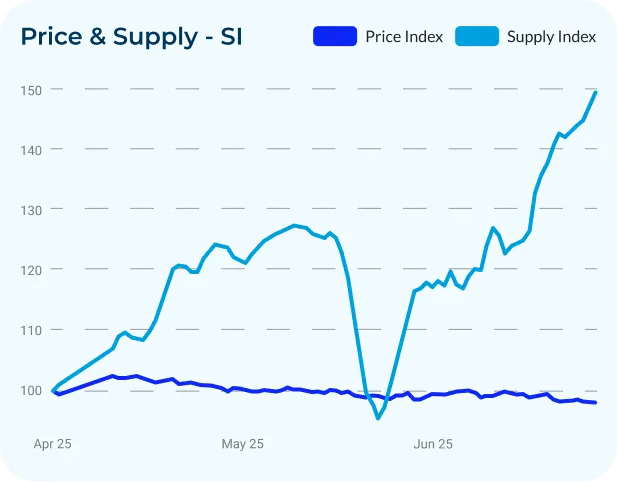
SI stones also remained relatively steady through Q2, with prices decreasing by just 1.8%, slightly more than Q1’s minimal 0.6% decrease, but still within a stable range. Supply increased significantly, climbing 49% across the quarter compared to a 34.2% reduction in Q1. The price resilience in the face of rising supply suggests that demand for 2ct SI goods held up well, though the elevated inventory levels may put pressure on pricing if demand softens in the quarters ahead.
Round 3ct Stones
The 3ct category remained steady in Q2 2025, continuing the strong performance seen in Q1, where prices held firm across both VS+ and SI clarity groups.
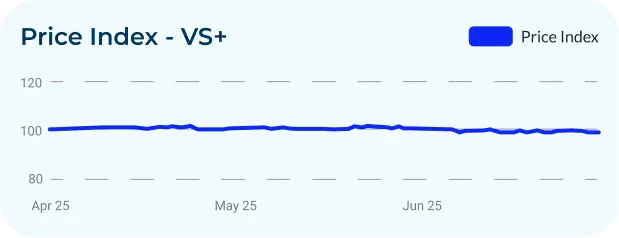
VS+ stones saw a minor price decline of just 1% over the quarter, a continuation of Q1’s modest 3% decrease and further evidence of price stability. Supply increased sharply during the quarter, but prices held steady, supported by consistent demand in this high-value segment.
SI stones also held steady during Q2, ending the quarter with only a 1% price decline, similar to Q1, where prices remained flat. Inventory also grew, but pricing remained stable, pointing to ongoing buyer interest.
Key Insights
The US Tariff Decision Is Casting a Long Shadow
Ongoing uncertainty around potential new US tariffs has led many in the trade to adopt a cautious stance. While the impact has not yet disrupted pricing, it’s contributing to a watch-and-wait approach, especially among American buyers. As one of the industry's most important markets, any concrete decision on tariffs could become a key turning point in Q’s 3 & 4 2025.
Pricing Stability Signals a Maturing Market
For the second consecutive quarter, the market avoided sharp corrections. With most price changes under 3% across all major size and clarity categories, the industry is clearly settling into a phase of slow, steady rebalancing rather than reactionary movement. This is especially evident in the larger 2ct and 3ct categories, where price stability held firm despite a surge in supply, a trend made even more significant given the ongoing tariff uncertainty and increased movement of goods into the US market.
Rising Supply Is Not Yet Disrupting Prices
Several segments, particularly 2ct and 3ct stones, saw major increases in supply during Q2. Yet prices remained steady or dipped only slightly, suggesting that demand remains strong enough to absorb new inventory. However, if this upward supply trend continues into Q3 without a matching rise in buyer activity, we may begin to see pressure on pricing.
SI Clarity Goods Show More Moderate Price Declines
After sharp decreases in Q1, SI stones across nearly all size categories experienced smaller price declines in Q2, or remained flat. This trend is especially notable in smaller goods, which were under heavy pressure throughout 2024 and early 2025 due to the growing influence of lab-grown alternatives. While still impacted by rising inventory levels, the moderation in price decreases and more stable supply patterns suggest that the SI segment may be beginning to find its floor.
Conclusion
Q2 2025 reinforced the trend of market stabilization, with modest price movements and measured shifts in supply across most segments. Pricing held steady across the quarter, even as supply rose significantly in several categories, especially in 2ct and 3ct stones, signaling a more balanced relationship between inventory and demand.
VS+ stones continued to show resilience, with prices either stable or slightly improved in most size groups. At the same time, SI goods, while still under some pressure, saw smaller price decreases compared to Q1, suggesting that this segment may be beginning to find its footing.
However, caution still defines much of the market's sentiment. The pending U.S. tariff decision remains a key variable for the rest of the year, and continued supply growth without a matching rise in demand could place pressure on prices in the months ahead.
As the market navigates these dynamics, UNI Diamonds' data-driven tools remain essential for tracking trends, adjusting strategies, and securing the right opportunities, in real time.
Ready to Elevate Your Diamond Trading?
Leave your details to book a demo and one of our representatives will get back to you as soon as possible!
 Search Registrant Register List - Dealers in Precious Metals and Stones Registration System